Higher yields are reshaping commercial real-estate lending, and the shift is opening a new buying window for retail assets, especially among investors with strong equity bases.
Retail Gains Attention as Yields Rise
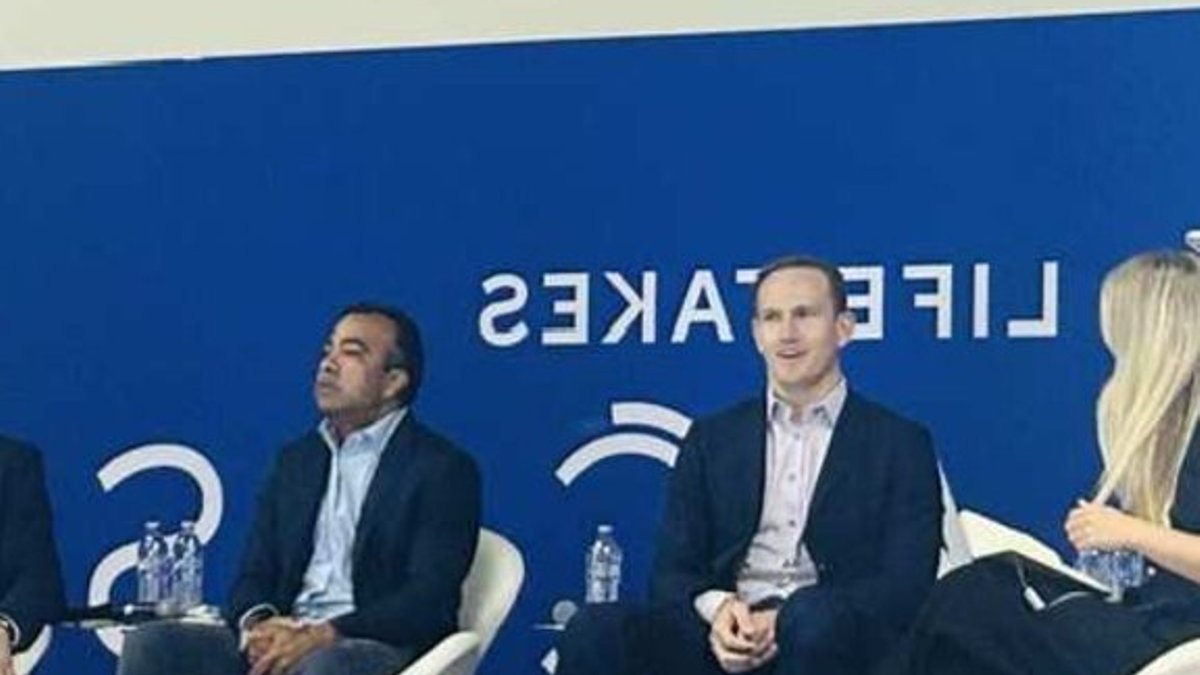
At the ICSC@Western deal-making event in San Diego, panelists noted that an influx of capital is intensifying competition for retail properties even as higher interest rates stretch buyer-seller expectations. The session, titled “Capital in Motion: Where is the Momentum in Today’s Market,” was moderated by Caitlin Zirpolo, vice president of investment sales at Colliers.
Panelists included Andrew Lundahl, vice president of private real estate at CenterSquare Investment Management; Sumeet Parekh, managing partner of HP Investors; and Jeffrey Sause, senior managing director and capital markets co-head at JLL. Lundahl described the current tilt toward retail as “one of the most significant changes in institutional investment sentiment since the 2008 financial crisis,” emphasizing that the sector has “right-sized itself” after the “Amazon effect.”
He added that retailers that survived the post-2008 downturn are now stronger, and institutional capital that once favored other CRE sectors is now targeting properties anchored by robust operators. “The pricing aggressiveness that was in the other food groups never got there for retail,” Lundahl said, noting that “institutional capital is fighting over good retail operators right now.”
Investors Adjust Strategies Amid Higher Rates
Higher borrowing costs are prompting a rethink of underwriting standards. With the 10-year Treasury yield hovering around 5%, financing expenses, seller expectations and market uncertainty are colliding, according to moderator Zirpolo. Despite these pressures, Sause said investor appetite for retail remains solid, with many participants eager to redeploy capital after missing deals in 2024 and 2025.
Dealmakers are extending exit-cap assumptions and focusing on assets that can sustain higher spreads. Parekh explained that his firm now underwrites larger spreads, avoids heavily vacant properties, and looks beyond California to secondary markets while scrutinizing tenant-improvement costs, which become more burdensome when capital is pricier.
Institutional investors are also showing interest in the value-add segment. Parekh said HP Investors has been approached by 6 to 8 institutional partners seeking to deploy capital in smaller deals or portfolios that historically fell below the institutional radar. “They are underallocated,” he said, adding that “it is hard for them to buy value-add retail without a partner.”
Local market knowledge and broker relationships give private operators an edge in sourcing such opportunities. Meanwhile, lenders have broadened the credit box over the past two years, creating additional sources of capital for retail acquisitions, Sause noted.
Credit Environment Expands
According to the discussion, lenders have considerably widened the range of financing options available for retail purchases over the past two years. This broader credit box includes a mix of traditional banks, life-insurance carriers and specialty debt funds, each willing to allocate more capital to transactions that meet stricter underwriting criteria.
Shifts in Deal Structuring
Because financing costs have risen, the importance of tenant-improvement budgets has grown. In this environment, cash-rich buyers are gaining leverage.